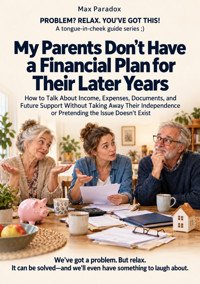
My Parents Don't Have a Financial Plan for Their Later Years - How to Talk About Income, Expenses, Documents, and Future Support Without Taking Away Their Independence or Pretending the Issue Doesn't Exist ebook
Max Paradox
29,99 zł
19,90 zł
Najniższa cena z 30 dni przed obniżką: 29,99 zł
19,90 zł
Najniższa cena z 30 dni przed obniżką: 29,99 zł
Dowiedz się więcej.
- Wydawca: ALL-IN Rafał Płonkowski
- Kategoria: Biznes, rozwój, prawo•Biznes, rozwój
- Język: angielski
Your parents have a plan for their later years. Probably. They've said, "We'll manage," and your father once successfully repaired a washing machine with a screwdriver and extraordinary self-belief. Surely retirement will be fine.
But what happens when income changes, the bills keep arriving, and everyone assumes someone else knows where the important documents are? How do you ask whether your parents can afford future support without making them feel as though you've arrived to seize control of their bank accounts, house, and television remote?
My Parents Don't Have a Financial Plan for Their Later Years is a sharp, warm, and practical guide to one of the most awkward conversations in family life: money between adult children and their parents.
Max Paradox explores why reassuring phrases can hide unanswered questions, why a seemingly healthy household budget may omit expensive realities, and why a valuable home isn't the same thing as money available to pay next month's bills. You'll learn to distinguish genuine warning signs from ordinary privacy, discuss income and debt without humiliation, and understand what an emergency fund actually needs to do.
The book also tackles the difficulties that rarely fit into a tidy spreadsheet. What if three siblings have four opinions about who should help? What if your parents want assistance with a task but not a new financial manager? What happens when care costs money, time, and energy that nobody has agreed to provide? How do you handle an emergency when the plan is still sitting in somebody's imagination?
Through recognizable family situations, dry humour, and grounded explanations, the book shows how to turn uneasy discussions into small, realistic decisions. It covers practical document organization, checking possible benefits with authoritative sources, assessing housing choices, setting limits on financial help, and revising arrangements when life changes.
Rather than demanding every account statement, you can ask questions that identify the real risk. Rather than promising unlimited help, you can describe what you can sustain. And rather than confusing a parent's expensive choice with financial incapacity, you can discuss consequences while leaving decisions where they belong.
This guide doesn't assume every family has spare money or perfect relationships. When essentials cost more than dependable income, cheerful advice about cancelling subscriptions isn't going to save the day. It addresses those difficult situations without pretending that every financial problem has a painless solution.
Most importantly, this isn't a manual for taking over your parents' lives. Their independence, preferences, and privacy matter. So do your time, finances, and right to say what you can genuinely offer. The aim is to find better ways to talk, understand what is known and what still needs checking, and make support workable without turning every Sunday lunch into an audit.
For adult children worried about their parents' financial future, and families who would rather communicate before the situation becomes urgent, this is an approachable guide to navigating difficult questions without losing either perspective or a sense of humour.
This publication was prepared using tools that support the creative process, including artificial intelligence solutions. The final concept, structure and editing are the responsibility of the author.
Ebooka przeczytasz w aplikacjach Legimi lub dowolnej aplikacji obsługującej format:
Liczba stron: 242
Rok wydania: 2026
Podobne
Cover
My Parents Don't Have a Financial Plan for Their Later Years
How to Talk About Income, Expenses, Documents, and Future Support Without Taking Away Their Independence or Pretending the Issue Doesn't Exist
Max Paradox
PROBLEM? RELAX. YOU'VE GOT THIS!
ISBN: 978-83-8483-768-9
ALL-IN Rafał Płonkowski
Table of contents
Title page
INTRO
Chapter 1 - Do Your Parents Really Have No Financial Plan, or Have You Simply Never Seen It?
Chapter 2 - Why Talking About Money Can Feel Like a Hostile Takeover
Chapter 3 - Hope Is Not a Retirement Strategy, Even When It Has Worked for Forty Years
Chapter 4 - The Household Budget Looks Fine Until You Count the Expenses Nobody Remembers
Chapter 5 - The Debt Nobody Talks About Still Has to Be Paid
Chapter 6 - Three Siblings, Four Opinions, and One Family Support Plan Nobody Agreed To
Chapter 7 - When Helping Your Parents Means Taking Over Without Realizing It
Chapter 8 - The Important Documents Are Somewhere Safe. Unfortunately, Nobody Knows Where
Chapter 9 - What Actually Comes In? Counting Income Without Auditing Your Parents' Wallets
Chapter 10 - An Emergency Fund Is Only Useful If You Can Actually Use It
Chapter 11 - When Your Parents Need Help, Who Is Going to Pay for It?
Chapter 12 - The Family Home: Valuable Property, Expensive Responsibility, and the Place They Still Want to Live
Chapter 13 - Are We Entitled to Any Help? Finding Real Support Among the Rumours
Chapter 14 - From Difficult Conversations to Decisions That Actually Happen
Chapter 15 - When There Really Isn't Enough Money, and There's Nothing Left to Cut
Chapter 16 - The Emergency Arrived Before the Plan: What to Do When Nobody Has the Instructions
Chapter 17 - When the Plan Falls Apart: Fixing What Failed Without Starting a Family War
Chapter 18 - A Financial Plan Doesn't Need Constant Supervision, but It Does Need an Occasional Check
Chapter 19 - When the Silence Returns: Spotting Financial Trouble Without Becoming a Family Detective
Chapter 20 - The Best Financial Plan Leaves Your Parents in Charge
Landmarks
Cover
Title page
Table of contents
Start of content
INTRO
Your mother calls on a Tuesday evening to ask whether you know a cheaper electricity provider. A perfectly reasonable question. You explain what she should compare, warn her about complicated contracts, and feel rather pleased with yourself for being useful. Then, just before hanging up, she casually adds, "We might need a little help with the bills when your father stops working." You ask what she means by "a little." She doesn't know. You ask when your father intends to retire. They're still discussing it. You ask whether they've calculated their future income. "Oh, don't start worrying about everything," she says. Five minutes ago, you were discussing electricity. Now you're apparently the emergency funding department for a retirement plan nobody has written.
The unsettling part isn't necessarily that your parents will need financial help. Plenty of families support one another, and there is nothing shameful about that. What troubles you is the complete absence of boundaries around the possibility. Are they imagining occasional assistance with unexpected expenses, a regular contribution to household bills, or something considerably more demanding? Do they have savings? Are there outstanding loans? Have they considered what would happen if one of them needed practical help at home? You don't know, and they seem remarkably comfortable with the situation. Meanwhile, your imagination has already produced seventeen increasingly expensive scenarios, none of which includes you enjoying a relaxing weekend.
Before deciding that your parents have completely neglected their future, however, consider something important: not knowing their financial arrangements doesn't necessarily mean those arrangements don't exist. Your parents managed money long before you had a bank account. They may have savings, investments, insurance arrangements, or simply a careful understanding of what they can afford. They might also have serious gaps in their preparation. The point is that assumptions are a terrible substitute for information, especially when those assumptions concern someone else's finances. A parent who dislikes discussing money isn't automatically irresponsible. Equally, a confident declaration that everything is under control doesn't prove that someone has considered what might change.
Retirement planning is particularly awkward because the past can provide misleading reassurance. Your parents may have spent decades successfully dealing with bills, repairs, family expenses, and unpredictable circumstances. They have genuine experience handling difficulties. But some of the resources that helped them before may change. Employment income might end. Additional work may become less appealing or less practical. Housing costs and other essential expenses will continue, even if the household's income changes significantly. A strategy that worked beautifully during working life may need adjusting. Unfortunately, "We've always managed" describes an impressive history, not necessarily a workable forecast. Experience deserves respect, but it cannot personally negotiate next year's bills.
There is another complication: your parents may hear an entirely different conversation from the one you believe you're having. You think you're asking whether their future income will cover their living expenses. Your father hears an accusation that he's failed to provide for his family. You want to understand where important documents are kept. Your mother hears a suggestion that she can no longer be trusted to manage her own affairs. Suddenly everyone is defending a position nobody intended to attack. Money is connected to independence, privacy, identity, and decades of personal choices. When adult children begin asking detailed questions, parents can feel as though the family hierarchy is being reorganized without consulting the people supposedly in charge.
Your own circumstances matter just as much. Perhaps you have children, housing payments, an unpredictable job, or savings goals that already demand careful decisions. You love your parents, but you cannot promise unlimited money, endless availability, or a permanent solution to every future problem. You may even feel guilty admitting that. Families are often excellent at expressing support in sweeping language and considerably less skilled at defining what it means. "Of course we'll help" sounds wonderful until somebody needs to know whether that means two afternoons a month or a substantial monthly payment for the foreseeable future. Affection doesn't make resources infinite, and honest limitations are more useful than generous promises nobody can maintain.
A workable financial plan doesn't have to resemble an investment prospectus. At its heart, it involves understanding which income is reasonably dependable, what maintaining everyday life actually costs, which financial commitments already exist, and what resources could help when circumstances change. It also means knowing how essential information can be found and what kinds of assistance might become necessary. The answers don't have to be elegant. Your parents might prefer paper records, simple calculations, and conversations with trusted institutions rather than elaborate software. That's fine. The important distinction is between an arrangement they understand and can use, and a comforting collection of statements beginning with "We should be all right."
Nor will every family need the same solution. Some parents have substantial assets but limited accessible cash. Others live comfortably on modest incomes because their expenses are predictable. Some carry debts they are managing responsibly; others struggle with obligations they are embarrassed to discuss. One parent may handle virtually every financial task while the other knows little about the arrangements. There are also families in which the available income genuinely cannot cover essential needs, no matter how carefully everyone shops. Those circumstances cannot be fixed by motivational speeches about discipline or by cancelling a subscription that doesn't exist. Useful planning must accommodate actual resources, not the imaginary household featured in cheerful money-saving advice.
The temptation, once you realize how much you don't know, is to take over. You offer to manage the accounts, sort the paperwork, contact every institution, and supervise financial decisions. Efficiency improves immediately, at least from your perspective. Unfortunately, your parents may experience the arrangement as an unsolicited takeover. Helping someone understand a document isn't the same as deciding what they must sign. Supporting them with a payment doesn't automatically entitle you to inspect every purchase. And having the technical ability to access an account isn't necessarily permission or legal authority to operate it. There are safer, properly authorized ways to arrange assistance when required. Respecting those boundaries is part of preparing responsibly, not an inconvenient obstacle to getting things done.
So where should a conversation begin? Usually with a real question rather than a comprehensive demand for financial disclosure. If your father is approaching retirement, you might ask whether he and your mother have considered how their regular income will change. If they're concerned about maintaining their home, ask which expenses worry them most. You can explain why the answer matters to you without insisting that they reveal everything immediately. Listen carefully, including when their response differs from what you expected. You may discover a problem that needs attention, a plan you hadn't known about, or simply a subject they aren't ready to discuss. Each outcome gives you a better starting point than an argument built on guesses.
Some circumstances do require greater urgency. Unpaid essential bills, suspected fraud, coercion, or serious difficulty understanding financial commitments may call for timely assistance from qualified professionals or relevant services. Financial and legal arrangements also vary between countries and individual circumstances, so general advice cannot replace an assessment of specific rights, contracts, or entitlements. But ordinary uncertainty should not automatically be treated as an emergency. Preparing for possible difficulties is sensible; behaving as though disaster has already arrived can make cooperation much harder.
This book is about finding a more useful middle ground. You'll learn to distinguish real financial vulnerabilities from uncomfortable unknowns, ask questions that lead somewhere, recognize misleading assumptions, and turn concerns into practical decisions. You'll consider how income, expenses, documents, housing, debts, and future assistance fit together, including the awkward situations where relatives disagree or the money simply isn't enough. There will be no promise that one perfect conversation solves everything. There will, however, be room for mistakes, changing circumstances, sensible boundaries, and the occasional absurdity that comes with trying to organize a family.
Your parents are still adults with their own preferences, histories, and rights. You are still an adult with responsibilities and limits of your own. A good plan should make those realities easier to live with, not erase them. The aim isn't to appoint yourself chief financial officer of your parents' remaining years. It's to help create enough clarity that nobody has to rely entirely on silence, assumptions, or a heroic last-minute rescue. And perhaps, the next time your mother calls about an electricity bill, you can discuss the electricity bill without accidentally accepting an open-ended contract to finance the rest of everyone's lives.
Chapter 1 - Do Your Parents Really Have No Financial Plan, or Have You Simply Never Seen It?
Your father has just announced that he and your mother are going on a three-week holiday. They're delighted. They've chosen the accommodation, booked the transport, and already started debating how many pairs of shoes a person reasonably needs for twenty-one days. You feel pleased for them until your mother casually mentions that they've postponed repairing a leak in the bathroom because the work is expensive. Suddenly, the holiday looks less like a well-deserved treat and more like evidence of questionable financial judgment. You wonder whether they have savings, how much their retirement income covers, and whether they'll eventually expect you to contribute. Your father, meanwhile, is explaining why he needs a new suitcase. Apparently, the financial future of the family has become deeply concerning to everyone except the people packing for it.
What exactly have you learned? You know your parents are paying for a holiday. You know there's a bathroom problem they haven't repaired. You don't know whether they have ample savings, whether the leak requires urgent attention, or why they've chosen to delay the work. Perhaps the holiday was budgeted for years ago and the repair can safely wait. Perhaps your parents have misunderstood the seriousness of the leak. Perhaps they're spending money they genuinely cannot afford to lose. These possibilities call for different responses, yet it's remarkably easy to settle on the most alarming explanation before asking a single useful question. Concern has a talent for turning missing information into convincing evidence.
The first distinction worth making is between financial vulnerability and your own uncertainty. They can overlap, but they aren't identical. You might know very little about your parents' finances because they've always considered money a private matter. They might have an entirely reasonable system that they don't particularly want to discuss. Conversely, parents who freely announce their savings balance at family gatherings can still be financially unprepared. Openness isn't the same as security, and secrecy isn't automatically evidence of trouble. Your task is to discover whether there is a meaningful gap in their preparation without treating their decision to maintain privacy as a problem in itself.
A financial plan needn't look impressive to be useful. Your parents might never have written one down. They may simply know their reliable income, understand their regular commitments, maintain accessible savings, and have considered how to respond to larger expenses. The arrangement could be basic but workable. Equally, a beautifully organized folder of statements might conceal a household that consistently spends more than it receives. The quality of preparation depends less on presentation than on whether the assumptions hold up when ordinary circumstances change. A color-coded spreadsheet is not inherently safer than a notebook. It merely has more opportunities to display mistakes in attractive colors.
Consider two imaginary households. The first consists of retired teachers living on relatively modest incomes. They understand their essential costs, have no significant unresolved debt, and can identify which expenses they could change if necessary. Their savings aren't spectacular, but they know their limitations and plan accordingly. The second household receives considerably more money, owns valuable possessions, and appears comfortable. Yet its members depend on irregular earnings to cover recurring bills, underestimate annual costs, and disagree about what would happen if one income disappeared. Which household is better prepared? The answer isn't automatically the wealthier one. Financial resilience depends on the relationship between resources, commitments, and realistic options, not merely the size of the figures involved.
This is why appearances are such unreliable witnesses. A parent who drives an old car may be financially secure and simply uninterested in replacing something that works. Someone who regularly travels may have planned those expenses carefully. A homeowner might possess a valuable property but struggle with the cash needed for maintenance. Conversely, someone renting a small apartment could have substantial savings and manageable expenses. You cannot determine financial preparedness by examining furniture, clothing, holidays, or how often your mother reminds everyone to switch off unnecessary lights. Those observations may suggest questions. They rarely provide definitive answers.
It helps to examine the underlying situation through four connected areas: dependable income, actual living costs, financial commitments and reserves, and arrangements for obtaining information or assistance when needed. The fourth area is especially easy to underestimate. A household can afford its expenses while relying entirely on one person's memory to manage insurance, banking, and essential paperwork. If that person becomes temporarily unavailable, the other may struggle with tasks that were previously straightforward. This doesn't automatically mean the household needs a different decision-maker. It means the people involved should understand how the household would continue functioning without relying on one individual's constant presence.
Start with income, but resist the temptation to demand exact figures immediately. What matters initially is whether your parents understand which payments they can reasonably depend upon. Retirement benefits, occasional employment, rental income, investment withdrawals, and financial assistance from others have different characteristics. A household that covers its essential expenses using reliable income is in a different position from one that must continually secure extra work to make ends meet. The second arrangement may still be manageable, particularly if the parents understand the risks and maintain alternatives. But if they assume an uncertain payment will arrive indefinitely, they may be relying on a condition that deserves closer examination.
Living costs require the same attention to context. Your parents may confidently describe what they spend each month while excluding expenses that occur less frequently. Insurance renewals, property maintenance, transport repairs, and essential equipment replacements don't cease to exist merely because they aren't monthly transactions. A person can pay every regular bill and still gradually deplete savings because the annual picture was never considered. However, you don't need access to every receipt to determine whether your parents recognize these costs. A useful initial question might be whether they allow for larger predictable expenses when assessing how much money is available. Their answer could reveal a sound approach, a misunderstanding, or simply a preference not to discuss the details.
Financial commitments deserve particular care because their significance isn't always visible. A loan with manageable repayments may be entirely consistent with a sensible plan. Several overlapping obligations, especially those used to finance ordinary living expenses, may create greater vulnerability. Yet simply discovering that your parents owe money doesn't establish that they're in trouble. You need to distinguish an obligation they understand and can meet from one they struggle to manage. Similarly, savings should be considered in terms of their intended purpose and accessibility. Money earmarked for a known upcoming expense isn't necessarily available to cover an unrelated emergency. These distinctions matter more than collecting impressive totals.
The practical arrangements surrounding money are also part of the picture. Do both parents understand the broad financial position of their household? Does each know how to obtain help with important matters if the other is unavailable? Are arrangements for sharing information or authorizing assistance appropriate and secure? A parent may be perfectly capable of making decisions but prefer someone else to handle certain technical tasks. That preference isn't evidence of incapacity. Nor does family membership automatically grant authority to access accounts or sign documents. Any formal arrangements should reflect the relevant institution's requirements and applicable law. The useful question is whether assistance can be obtained appropriately when necessary, not whether you personally possess every password.
Before approaching your parents, try separating what you actually know from what you've inferred. Take a page and create three simple headings: confirmed information, interpretations, and unanswered questions. Under confirmed information, place facts you have reliable grounds to believe, such as a parent having recently retired or asking for help with a particular payment. Under interpretations, put conclusions that might be mistaken: "They never discuss savings, so they probably have none." Under unanswered questions, identify information that would genuinely change your understanding, such as whether essential expenses remain affordable after retirement. This exercise prevents your fears from quietly graduating into facts without completing the examination.
Be careful about the evidence you collect. You aren't conducting an investigation into suspected criminal activity. Searching private correspondence, opening financial statements without permission, or asking relatives to report on your parents' purchases can damage trust without producing a reliable financial assessment. Even information shared casually by another family member may be incomplete. Your aunt's confident declaration that your father has "never understood money" might reflect an argument they had in 1994 about the purchase of a lawnmower. Unless you're dealing with a genuine safety concern requiring appropriate intervention, respectful conversation is a much better starting point than surveillance.
Some warning signs do justify a more focused response. Repeated requests for money to cover basic necessities, unpaid essential bills, unexplained collection notices, or continuing difficulty meeting existing commitments deserve attention. So do concerns about financial coercion or someone pressuring a parent into transactions they don't understand. These signs don't prove a particular diagnosis or establish that an adult has lost the ability to manage their affairs. They indicate that a concrete problem may require prompt clarification and, in serious circumstances, professional assistance. The appropriate response depends on the nature and urgency of the risk. A suspicious financial solicitation and a disagreement about holiday spending should not receive the same treatment.
Another possibility is that your parents are prepared for the future, but their plan includes decisions you dislike. They may intend to remain in a costly home because it matters deeply to them. They may choose to spend some savings while they're healthy enough to enjoy particular activities. You can discuss the likely consequences, particularly where future assistance from you might be involved, without assuming that your preferred choice is the only rational one. Financial planning involves priorities as well as arithmetic. Provided an adult understands the implications and can decide freely, a different set of preferences doesn't automatically make the decision irresponsible.
Suppose your parents explain that their basic expenses are covered and that they've allowed for foreseeable larger costs, but they decline to disclose their account balances. You may dislike the uncertainty, especially if you're someone who prefers detailed information. Nevertheless, you now know something useful: they have considered particular aspects of the problem and are setting a boundary around private financial details. Whether that reassurance is sufficient depends on the circumstances. If they're simultaneously asking you to fund a substantial monthly shortfall, you reasonably need more information before agreeing to support them. If they're financially independent and showing no signs of serious difficulty, your curiosity alone doesn't create an entitlement to their records.
Your choice of question should therefore follow the concern you're trying to resolve. If you're worried about a change in retirement income, ask how they're adjusting to that change. If the issue is a major financial commitment, ask whether its ongoing cost remains manageable. If you're concerned about your potential future responsibilities, explain that you'd appreciate knowing what kind of help they might eventually want, while making clear you cannot promise unlimited support. One relevant question usually reveals more than a twenty-question financial interrogation. It also gives your parents room to explain their reasoning rather than defend themselves against a verdict you've already reached.
You may eventually discover that your concerns were justified. Perhaps your parents have insufficient income, no realistic reserve, or commitments that require urgent attention. Finding that out doesn't mean the solution will be simple. Low income cannot always be corrected through better habits, and some decisions involve difficult trade-offs. The value of understanding the situation is that you can stop guessing and identify the actual obstacle. Sometimes that leads to a manageable change. Sometimes it leads to a conversation with a qualified adviser, a relevant service, or an institution able to explain available options. Either outcome is more useful than trying to solve every hypothetical problem at once.
Your parents' financial future is not a puzzle you must solve without their participation. It is their life, containing information you may not possess and priorities you may not share. Start by identifying what you know, what concerns you, and what would genuinely help clarify the situation. Give the evidence an opportunity to disagree with your imagination. You might discover a problem that needs addressing, a reasonable arrangement you never knew existed, or a mixture of both. The achievement is not obtaining complete access to the family finances. It is reaching a more accurate understanding without mistaking your parents' independence for an obstacle to be removed.
Chapter 2 - Why Talking About Money Can Feel Like a Hostile Takeover
Oliver has prepared a thoughtful presentation for his parents. There are six slides, a modest financial projection, and a heading that reads "Planning for the Years Ahead." He's even chosen a cheerful photograph for the opening slide because he doesn't want the conversation to feel depressing. His parents arrive expecting lunch. Before the food is served, Oliver connects his laptop to the television and announces that he'd like to discuss their retirement arrangements. His mother looks at the screen. His father looks at Oliver. "Are we being audited?" he asks. Oliver laughs nervously and explains that he's only trying to help. Twenty minutes later, his mother is offended, his father has refused to discuss his savings, and Oliver is wondering how a presentation featuring smiling people on a beach managed to create such a thoroughly unpleasant afternoon.
The problem wasn't necessarily the information. Oliver's questions might have been reasonable, and his concerns could have been genuine. The difficulty was that he'd decided how the conversation would happen before discovering whether his parents wanted to participate. He selected the subject, the timing, the format, and the questions. He then presented the arrangement as helpful, apparently forgetting that his parents were adults capable of having opinions about all four. From their perspective, the presentation wasn't an invitation to plan together. It was an announcement that their son had appointed himself chairman of a committee they hadn't agreed to join. The smiling people on the beach were merely decorative witnesses.
Money conversations are unusually sensitive because financial decisions represent much more than transactions. They express preferences, priorities, independence, and sometimes a person's sense of accomplishment. Your parents may have spent decades supporting a household, choosing what to buy, deciding when to save, and accepting responsibility for mistakes. They might reasonably feel proud of having managed those decisions, particularly if circumstances were difficult. When an adult child begins asking whether they've made adequate arrangements for old age, the question can sound like a judgment on everything that came before. You may be asking, "What happens when your income changes?" They may be hearing, "After all these years, have you finally admitted you don't know what you're doing?"
Family roles make this especially complicated. As a child, you probably weren't invited to approve household budgets or evaluate your parents' financial decisions. You might have been instructed to turn off lights, avoid wasting food, and understand that money doesn't grow on trees, although no one ever explained why it seems to disappear from bank accounts quite so enthusiastically. Your parents made the major decisions. Now you're an adult with your own financial experience, and you may genuinely understand some matters better than they do. Yet the emotional relationship doesn't reorganize itself as neatly as professional responsibilities. Your father can accept your help comparing financial products while still resenting the suggestion that you should supervise his spending.
For some families, financial privacy is an especially powerful convention. Parents may have grown up believing that income, savings, and personal debt should never be discussed outside a very small circle. Others learned to avoid money conversations because they were associated with arguments, uncertainty, or humiliation. You don't need to assume a dramatic psychological history to recognize that these conventions matter. A parent who considers account balances intensely private may experience a direct question about savings as intrusive, even when your intention is entirely practical. Telling them that they have "nothing to hide" doesn't help. Privacy isn't automatically evidence of wrongdoing, and people don't surrender it simply because another person believes disclosure would be convenient.
Embarrassment complicates both ends of the financial spectrum. Parents with limited resources may feel they've failed to prepare adequately, especially if they once expected to enjoy a comfortable retirement. They may fear becoming a burden or being judged for decisions that seemed reasonable at the time. Parents with substantial assets can be equally reluctant to disclose them, perhaps because they worry about requests for money, disagreements over future inheritance, or changes in how their children treat them. The same refusal to discuss savings might arise from completely different concerns. If you assume that silence always means financial difficulty, you could spend an entire conversation trying to solve a problem that isn't there while ignoring the fear that actually matters.
Another obstacle is the way discussions about money become entangled with ageing. Asking your mother how she would manage household expenses if she couldn't do everything herself may remind her of possibilities she'd rather not contemplate. Questions about access to documents can sound like preparations for her absence. A conversation about future assistance might seem to suggest that you expect her independence to disappear. These reactions aren't necessarily irrational. Planning does involve acknowledging uncertainty, and uncertainty can be uncomfortable. Your job isn't to persuade your parents that they should feel nothing. It's to explain the practical purpose of a question without turning the conversation into an unnecessarily alarming forecast of their decline.