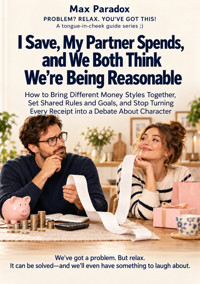
I Save, My Partner Spends, and We Both Think We're Being Reasonable - How to Bring Different Money Styles Together, Set Shared Rules and Goals, and Stop Turning Every Receipt into a Debate About Character ebook
Max Paradox
29,99 zł
19,90 zł
Najniższa cena z 30 dni przed obniżką: 29,99 zł
19,90 zł
Najniższa cena z 30 dni przed obniżką: 29,99 zł
Dowiedz się więcej.
- Wydawca: ALL-IN Rafał Płonkowski
- Kategoria: Biznes, rozwój, prawo•Biznes, rozwój
- Język: angielski
Two people. One relationship. Completely different ideas about what counts as sensible spending. What could possibly go wrong?
You save money because the future is unpredictable. Your partner spends money because life is happening right now. You see a reassuring savings balance. They see opportunities worth enjoying. You call it responsibility. They call it living. And somehow, an innocent purchase of a household item turns into a passionate debate about maturity, trust, childhood, and whether either of you understands basic mathematics.
Welcome to the wonderfully complicated world of couples and money.
In I Save, My Partner Spends, and We Both Think We're Being Reasonable, Max Paradox takes a humorous, practical look at one of the most persistent sources of relationship tension: loving someone whose financial instincts seem to have been developed on another planet.
This isn't a book about transforming a spender into a saver or teaching a cautious partner to abandon every financial concern. It's about understanding why two intelligent people can examine the same expense and reach completely different conclusions, then learning how to make decisions without turning those differences into personal accusations.
You'll discover how family experiences shape attitudes toward money, why seemingly sensible budgets fail in real life, and how to recognize expenses that quietly undermine your plans. You'll also explore the difference between financial privacy and harmful secrecy, the hidden work involved in managing household finances, and the emotional habits that make both spending and excessive saving difficult to control.
Most importantly, the book offers practical ways to build a financial arrangement that works for two different people.
Learn how to separate shared household expenses from savings goals and individual spending, set realistic financial priorities, and approach substantial purchases without turning every decision into a courtroom drama. Explore what fairness means when partners earn different amounts, how to handle financial requests from relatives, and what to do when your attitudes toward investing and risk are miles apart.
The book also addresses situations where ordinary budgeting advice is insufficient: hidden debts, repeated broken agreements, financial dependence, unexpected expenses, and households where there genuinely isn't enough money to cover everything.
Rather than promising a magical formula, Max Paradox shows how to recognize the real issue, discuss consequences honestly, establish workable boundaries, and adjust your plans when circumstances change.
With relatable situations, sharp observations, and humor drawn from everyday financial absurdities, this guide helps you stop treating every purchase as evidence in a trial of your partner's character.
Because a healthy relationship doesn't require identical spending habits. It requires trust, reasonable independence, shared responsibility, and enough common sense to know when a receipt is just a receipt.
Perfect for couples who want fewer money arguments, clearer financial agreements, and the freedom to remain themselves.
Your partner may never understand why you love saving money. You may never understand why they needed that particular purchase.
You can still build a good financial life together.
This publication was prepared using tools that support the creative process, including artificial intelligence solutions. The final concept, structure and editing are the responsibility of the author.
Ebooka przeczytasz w aplikacjach Legimi lub dowolnej aplikacji obsługującej format:
Liczba stron: 245
Rok wydania: 2026
Podobne
Cover
I Save, My Partner Spends, and We Both Think We're Being Reasonable
How to Bring Different Money Styles Together, Set Shared Rules and Goals, and Stop Turning Every Receipt into a Debate About Character
Max Paradox
PROBLEM? RELAX. YOU'VE GOT THIS!
ISBN: 978-83-8483-660-6
Table of contents
Title page
INTRO
Chapter 1 - Two Sensible People, One Bank Balance, and Completely Different Ideas of Reasonable
Chapter 2 - The Money Rules You Inherited Without Ever Agreeing to Them
Chapter 3 - Where Did All Our Money Go? The Mystery of the Disappearing Paycheck
Chapter 4 - Brilliant Money Solutions That Somehow Make Everything Worse
Chapter 5 - How to Talk About Money Without Putting Your Entire Relationship on Trial
Chapter 6 - Secret Purchases, Hidden Debts, and the Expensive Business of Losing Trust
Chapter 7 - Bargains, Rewards, and Regret: The Spending Habits That Keep Pulling You Apart
Chapter 8 - The Invisible Job of Managing Money, and Why One Partner Never Gets a Day Off
Chapter 9 - Three Money Pools, Two Independent Adults, and No More Permission Slips for Every Purchase
Chapter 10 - Shared Goals Without Turning Your Dreams Into a Bidding War
Chapter 11 - One Big Purchase, Two Different Opinions, and a Decision Neither of You Wants to Regret
Chapter 12 - Your Emergency Fund Is Not a Museum Exhibit
Chapter 13 - Your Family, My Family, and Our Money: Who Are We Actually Helping?
Chapter 14 - One Wants to Invest, the Other Wants to Sleep: How Much Risk Can a Relationship Afford?
Chapter 15 - When One Earns More and the Other Contributes More Than a Paycheck Can Show
Chapter 16 - We Had an Agreement. So Why Are We Having the Same Argument Again?
Chapter 17 - When There Really Isn't Enough Money: Stop Arguing Over Dollars That Don't Exist
Chapter 18 - The Household Money Checkup That Doesn't Require a Board Meeting
Chapter 19 - When Old Money Habits Come Back Wearing New Clothes
Chapter 20 - You Don't Have to Spend Alike to Build a Good Life Together
Landmarks
Cover
Title page
Table of contents
Start of content
INTRO
The argument begins with two concert tickets and a sentence that should, in theory, be completely harmless: “I thought you'd be excited.”
One partner has spent $320 on tickets to see a favorite band. The concert is six months away, the seats are excellent, and the tickets sold out within minutes. This is not merely a purchase. It is a rare opportunity, a future memory, and possibly the most romantic surprise since someone voluntarily emptied the dishwasher without being asked. Unfortunately, the other partner is staring at a bank balance and thinking about the increasingly suspicious noises coming from the washing machine. Three hundred and twenty dollars could cover a repair. It could strengthen their emergency savings. It could remain safely in the account, where money traditionally behaves itself. Within ten minutes, the conversation has moved from live music to financial responsibility, mutual respect, and whether either person understands what adulthood involves. The band, blissfully unaware, continues selling merchandise.
Welcome to one of the strangest disagreements two otherwise sensible people can have. You can share a home, a future, and an impressive understanding of each other's most irritating habits, yet disagree completely about what money is supposed to accomplish. One person sees savings as freedom from uncertainty. The other sees spending as freedom to enjoy the opportunities available right now. One experiences relief when the account balance grows. The other experiences relief when money improves an ordinary Tuesday. Both believe they're making responsible choices, and neither particularly enjoys being informed that their definition of responsibility is apparently defective.
The interesting part is that neither position is necessarily unreasonable. Keeping money available for emergencies can be wise. So can deliberately spending some of it on meaningful experiences. The difficulty comes when we treat our preferred approach as an objective fact rather than a decision shaped by priorities, circumstances, and personal experience. “We can't afford that” may mean the money genuinely isn't available. It may also mean “I would rather protect our savings.” Meanwhile, “We deserve this” might express a reasonable wish to enjoy life, or it might be an exceptionally convenient explanation for an impulse purchase. The words sound decisive. The thinking underneath them deserves closer examination.
Money carries more emotional baggage than its remarkably slim physical dimensions would suggest. For some people, a healthy savings balance represents safety, independence, and the reassurance that one unexpected setback won't turn life upside down. For others, money represents choice, generosity, comfort, and the possibility of creating experiences that won't be available forever. These meanings often develop long before couples open joint accounts or decide who's responsible for the electricity bill. A person who once experienced financial instability may find uncertainty especially uncomfortable. Someone raised in a household where every enjoyable purchase was postponed might be determined not to spend adulthood waiting for permission to live. Understanding these influences doesn't mean accepting every resulting behavior. It means recognizing that your partner may be reacting to something more complicated than a price tag.
Unfortunately, most couples don't begin financial disagreements by explaining their deepest beliefs about security and enjoyment. They begin with considerably less diplomatic material. “Do you seriously need another one?” is a popular opening. So is “Why do you have to make everything about money?” The conversation then follows a predictable route: one person defends the purchase, the other questions the judgment behind it, and both gradually abandon the original subject. Eventually someone mentions a purchase made four years earlier that was supposedly forgiven, forgotten, and buried. Apparently, it was merely archived for future legal proceedings. The disagreement stops being about what to do with money and becomes an argument about who can be trusted to make decisions.
Many attempted solutions make things worse because they address the visible behavior without resolving the underlying disagreement. One partner introduces a detailed budget and expects the other to follow it. The other agrees to avoid an argument but privately considers the limits excessive. Someone proposes combining every account, believing shared money will automatically produce shared priorities. Someone else insists on keeping everything separate, hoping financial independence will eliminate conflict. Neither arrangement guarantees cooperation. A spreadsheet cannot manufacture agreement, and separate bank accounts cannot settle questions about household obligations, unequal incomes, or competing goals. Even the most beautiful budgeting application becomes useless when one person treats it as a shared plan and the other regards it as an unsolicited performance review.
There is also a difference between having contrasting spending habits and having a genuine financial problem. Buying expensive running shoes from an agreed personal allowance may be perfectly acceptable, even if your partner considers running outdoors a suspicious activity that should require no equipment whatsoever. Secretly taking money intended for rent is another matter. A couple can respectfully disagree about vacations, hobbies, and how much comfort is worth paying for. They cannot safely ignore unpaid essential bills, concealed debt, or commitments that neither person can realistically meet. Learning to distinguish preferences from harmful consequences is an essential part of making fair decisions. Without that distinction, couples either fight over harmless differences or excuse genuinely serious behavior as merely another personality trait.
Real life makes this more complicated than the tidy examples in personal finance articles. Partners don't always earn similar salaries, receive predictable paychecks, or have equal amounts of free time. One might manage most childcare while the other works longer hours. Someone may have variable income, medical expenses, family members who need support, or debts accumulated before the relationship began. Sometimes there genuinely isn't enough money to satisfy every reasonable need. No amount of positive thinking, color-coded budgeting, or enthusiastic advice about giving up takeaway coffee can solve a persistent gap between essential costs and available income. In those circumstances, the goal becomes making difficult choices fairly and protecting essential needs, not identifying which partner has failed the financial maturity examination.
This book will help you look at your money disagreements differently and, more importantly, respond to them differently. You'll learn to recognize what you're actually arguing about, distinguish practical concerns from assumptions about character, and have conversations that lead to decisions instead of emotional exhaustion. You'll explore ways to protect shared obligations while preserving personal freedom, establish realistic goals when your priorities differ, and handle larger purchases without turning every decision into a referendum on the relationship. You'll also consider what happens when agreements fail, circumstances change, or trust has been damaged. None of these approaches requires you to develop identical personalities or pretend that every disagreement can be solved by splitting the difference.
Some situations need more than a budgeting conversation. Concealed liabilities, serious financial hardship, and complicated legal obligations may require qualified financial or legal advice. Controlling access to essential money, threatening a partner over ordinary spending, or using financial dependence to force compliance are not simply different money styles. They are serious warning signs that can require independent support and attention to safety. A practical guide should help you recognize the limits of compromise, not persuade you that every problem disappears when both people speak politely enough.
You can begin with one small change. The next time a financial disagreement starts, resist the urge to decide immediately who is being unreasonable. Ask what each of you is trying to protect or achieve, what the decision will actually cost, and whose obligations it will affect. You may discover that one person wants security while the other wants some freedom to enjoy the present. You may also discover that the numbers don't support the purchase, regardless of how appealing it seems. Either discovery is more useful than a character judgment. You're looking for information that helps you make a decision, not ammunition for the next argument.
You don't need to love every purchase your partner makes. You don't need to stop caring about savings, and you certainly don't need to treat financial responsibility as an obstacle to happiness. You need enough honesty to see the consequences, enough flexibility to accommodate different priorities, and enough mutual respect to remember that you're managing a shared life rather than competing for the title of Most Sensible Adult.
The concert tickets might turn out to be an excellent decision. They might also need to be refunded. Either outcome is manageable when both people understand how the decision was reached.
And if you can discuss $320 without reviewing every questionable purchase since your first date, you're already getting something valuable for your money.
Peace, with no booking fee.
Chapter 1 - Two Sensible People, One Bank Balance, and Completely Different Ideas of Reasonable
The trouble begins in the luggage department.
Oliver is holding a suitcase that costs $289. It has sturdy wheels, a lightweight frame, a generous warranty, and a locking mechanism that the salesperson demonstrates with the seriousness of someone explaining security arrangements for a visiting head of state. His partner, Sophie, is standing beside a perfectly respectable suitcase priced at $94. It has wheels too. It closes. It holds clothes. From Sophie's perspective, these are rather important qualifications for employment as a suitcase. Oliver points out that they travel several times a year and the expensive model should last longer. Sophie replies that they could buy three cheaper suitcases for the same money. Oliver says buying cheap products repeatedly is wasteful. Sophie says paying nearly three hundred dollars for a box with a handle is ridiculous. Fifteen minutes later, neither is discussing luggage. Oliver is apparently incapable of understanding value, while Sophie is apparently incapable of enjoying anything decent. The salesperson quietly turns toward another customer, presumably someone traveling alone.
What makes this disagreement interesting is that both people have a reasonable argument. Oliver is thinking about durability, convenience, and the possibility of avoiding replacement costs. Sophie is thinking about the money available today and whether the additional features justify almost two hundred dollars. Neither position is inherently foolish. Yet both have begun treating their preferred definition of value as the only intelligent one. Somewhere between the wheels and the warranty, a practical purchasing decision has become a judgment about personal character. The suitcase hasn't even left the store, and it is already carrying considerably more emotional baggage than the manufacturer intended.
This happens because the word reasonable conceals an impressive number of competing meanings. To one person, reasonable means spending as little as possible while meeting a need. To another, it means paying more for something reliable. Someone else associates it with maintaining sufficient savings, choosing convenience, avoiding debt, or enjoying the rewards of hard work. All these principles can be useful. They can also conflict. When partners declare that a purchase is unreasonable, they often assume the definition is obvious and needs no further explanation. What they're effectively saying is, "If you saw the situation correctly, you would make my decision." This is an attractive position because it eliminates the exhausting possibility that another intelligent adult might value something differently.
The same amount can represent different things
Consider two people with $12,000 in accessible savings. One sees a reassuring cushion against unexpected expenses. The other sees an amount that is still dangerously small. Nothing about the balance changes between their interpretations. They disagree about which future difficulties deserve attention, how likely those difficulties seem, and how much protection would allow them to relax. If they discuss a vacation, the first person might feel comfortable spending some of the money while the second experiences genuine anxiety at the prospect. Calling one irresponsible and the other paranoid would be easier than discussing their expectations, but considerably less useful.
The same difference appears when money represents freedom. For the saver, freedom may mean being able to leave an unpleasant job, survive an interruption in income, or refuse an expensive commitment without panic. For the spender, freedom may mean being able to pursue an interest, enjoy time with loved ones, or make an occasional decision without preparing a financial defense statement. Both are looking for greater control over life. They simply locate that control in different places. One sees options preserved by money that remains untouched. The other sees opportunities created when money is deliberately used. Neither version captures the entire purpose of financial resources.
Time makes the disagreement even more complicated. A person thinking primarily about the next twenty years may regard today's discretionary spending as a reduction in tomorrow's choices. Someone concentrating on the next two years may worry that an opportunity available now will never return. These aren't necessarily opposing moral philosophies. Sometimes they're responses to very different assumptions about work, health, family responsibilities, and the uncertainty of the future. A sensible decision must consider both the resources that need protection and the experiences that matter while they remain possible. Saving everything indefinitely can be as disconnected from your actual goals as spending without considering tomorrow.
Of course, none of this means every purchase can be justified by attaching a meaningful personal value to it. Someone could describe a luxury watch as an investment in confidence, professional identity, and the fundamental dignity of knowing the time. Those descriptions don't establish affordability. If buying it means missing an essential payment, the consequences remain serious regardless of the story surrounding the purchase. Equally, refusing a necessary repair simply because spending causes discomfort may create larger costs later. Good judgment requires examining both the reason for a decision and what actually follows from it.
This is where financial arguments often go wrong. Couples debate whether an expense is morally acceptable before establishing its practical consequences. They might spend an evening arguing over a $150 purchase while ignoring an ongoing service that costs significantly more each year. The smaller purchase provokes an emotional reaction because one partner considers it frivolous. The recurring expense passes unnoticed because it feels familiar. Annoyance and financial significance are not the same thing. An expense can be irritating without being damaging, while a perfectly ordinary expense can quietly undermine an important goal.
Another complication is that few people maintain one consistent money personality across every category. A careful saver may spend enthusiastically on professional equipment, insisting that quality matters. The same person might refuse to replace an uncomfortable mattress because the existing one hasn't technically disintegrated. A more spontaneous spender might enjoy restaurants while being exceptionally cautious about borrowing. These apparent contradictions often reveal priorities rather than hypocrisy. The person who buys premium equipment values its particular benefits. The person who dislikes debt may value independence even while enjoying everyday indulgences. Labels such as "the saver" and "the spender" are convenient descriptions, but they become misleading when used as permanent explanations for everything someone does.
When disagreement becomes a character assessment
Imagine that Rachel subscribes to a paid service that saves her several hours of household administration each month. Her partner, Daniel, considers the subscription unnecessary because the tasks could be completed manually. Rachel thinks the cost is justified by reduced stress and the time she gets back. Daniel sees an expense that could be avoided with a little effort. Neither has yet established who would actually perform the work if the subscription were canceled. That detail matters. An apparent saving can require additional labor, and the person proposing it may not be the person expected to provide that labor.
If Daniel calls Rachel lazy, the practical question disappears beneath an accusation. If Rachel responds that Daniel cares more about money than her wellbeing, she has made a similarly sweeping judgment. They now face two separate disputes: whether the service is worth its cost and whether they respect each other's contribution. The second dispute can become much more painful than the first, especially if similar accusations have accumulated over time. A useful alternative is to describe the actual trade-off. How much does the service cost? What tasks does it replace? Who would perform those tasks otherwise? Could a less expensive option deliver enough of the benefit? Those questions cannot guarantee agreement, but they reveal what agreement would involve.
Try separating three elements of a disputed decision: the known facts, the expected consequences, and the personal priorities involved. The facts might include the amount, the payment date, the available funds, and any commitments already made. The expected consequences could include reduced savings, lower future costs, improved convenience, or the risk of needing a replacement. Priorities explain why particular consequences matter to each person. Someone may place a high value on predictability, while another prioritizes comfort or flexibility. These elements should be considered together, but they should not be confused. "This will destroy our savings" is a prediction requiring evidence, not a fact established by the speaker's level of alarm.
With the suitcase, Oliver and Sophie could discover that the difference in price would have little effect on their essential obligations but would delay a modest savings goal. They could compare genuine warranty coverage, repairability, weight, and likely usage rather than assuming the expensive option must last longer or the cheaper one must be sufficient. They might still choose differently if shopping alone. As a couple making a shared purchase, however, they would understand the trade-off. Perhaps they choose the cheaper case and reserve the difference for the trip. Perhaps frequent travel makes the premium model worthwhile. Either outcome is better grounded than accusing someone of being incapable of financial adulthood beside a display of luggage tags.
It also helps to notice what each partner is afraid of losing. The saver may fear financial security, but could also fear losing control over a future they have carefully planned. The spender may fear missing an enjoyable experience, but could also fear having to request permission for ordinary choices. These concerns deserve attention without being treated as automatic instructions. A fear can be genuine even when the feared outcome is unlikely. An opportunity can be appealing even when its cost is unjustified. Understanding an emotion allows you to consider it alongside the evidence instead of demanding either total obedience to it or complete suppression.
A disagreement doesn't always require a compromise
There's a widespread assumption that fair decisions must land somewhere between two initial positions. If Oliver wants a $289 suitcase and Sophie wants a $94 suitcase, perhaps $190 is the answer. Unfortunately, arithmetic doesn't automatically produce wisdom. A $190 suitcase could be worse than both alternatives. More importantly, some disagreements are about the right to decide rather than the amount involved. If Oliver is using money allocated for his own purchases and all shared obligations remain protected, Sophie may not need to approve his choice. If the money belongs to a joint savings goal, neither should unilaterally redirect it simply because the preferred purchase seems especially sensible.
Recognizing the difference between personal preferences and shared consequences prevents unnecessary conflict. You don't need identical tastes in clothes, entertainment, hobbies, or technology. You need clarity about which decisions affect both of you. A partner can find your chosen hobby baffling without having a legitimate claim to control every purchase associated with it. Equally, personal enthusiasm doesn't justify spending money already committed to rent, debt repayments, or a shared obligation. Independence and responsibility work best when the boundaries between them are understood rather than improvised during an argument.
Sometimes a disagreement reveals a serious issue that cannot be settled by respectfully accepting different preferences. Repeatedly concealing debts, ignoring essential bills, or committing shared money without consent requires direct attention to the consequences. Financial intimidation and restricting someone's access to necessary resources are more serious still. Those situations may require qualified financial, legal, or safety support. Calling every behavior a different money style can conceal real harm. The purpose of understanding your partner's perspective is to make better decisions, not to excuse actions that endanger the household or undermine another person's independence.
For ordinary disagreements, though, a small change in language can make a remarkable difference. Instead of asking, "How can you possibly think that's reasonable?" ask, "What makes this worthwhile to you?" The answer may reveal a benefit you've overlooked, an assumption you disagree with, or a practical problem neither of you has examined. Offer the same explanation for your own preference. Be specific about what you want to protect and what would make a proposed expense acceptable. You are not required to abandon your position merely because your partner provides an explanation. You are required to distinguish an explanation from an admission of guilt.
Consider two recent purchases that caused friction. For each, try describing your partner's reasoning in words they would recognize as fair, without adding an insulting interpretation. Then describe your own concerns with equal accuracy. If you struggle to explain what the other person actually valued, you may have been arguing against an assumption rather than their position. Ask them to clarify it. You might discover that the disagreement concerns a solvable practical detail, such as timing or available funds. Or you may find a genuine difference in priorities requiring a more deliberate decision.
The test of a good financial discussion isn't whether both people emerge with identical opinions. It's whether they can identify the decision, understand its consequences, and respect the boundaries involved. Someone who enjoys spending can learn from a partner's attention to risk. Someone who prefers saving can learn to recognize worthwhile benefits that don't appear as growing balances. Neither should have to surrender their personality to participate in a responsible financial partnership.
Oliver and Sophie might leave the store with the expensive suitcase, the affordable one, or no suitcase at all. What matters is whether the decision is understood rather than merely won. The case will eventually be scratched, dropped, and perhaps treated with surprising aggression by an airport baggage handler. Their relationship has no reason to suffer the same treatment over its purchase.
Chapter 2 - The Money Rules You Inherited Without Ever Agreeing to Them
At seven years old, Nina received five dollars from her grandmother and immediately placed it inside a small metal tin. The tin had once contained biscuits, although nobody in the family could remember when it had last performed that particular duty. Her father praised her for saving and explained that money was something you should always keep for later. A few streets away, a boy named Ben received five dollars for helping his uncle wash a car. His uncle took him to a small neighborhood shop, encouraged him to choose something he liked, and told him that earning money should occasionally lead to enjoying it. Neither child attended a financial education seminar. Neither learned about retirement planning, inflation, or household budgets. Yet both experienced something memorable: money was associated with approval, and that approval followed a particular kind of behavior.
Twenty-five years later, Nina and Ben are married. Nina feels pleased when she transfers money into savings, even if the amount is small. Ben enjoys treating people to meals and buying thoughtful gifts. He regards generosity as an important part of a good life. Nina considers planning ahead an expression of responsibility. Their disagreement isn't simply about whether to spend twenty dollars. Each has developed an intuitive understanding of what a responsible adult does with money. The remarkable thing is that neither remembers formally choosing these rules. They arrived gradually, through family routines, repeated comments, experiences of uncertainty, and moments of approval or disapproval. By adulthood, they feel less like lessons and more like common sense.
You may recognize some of your own rules immediately. Perhaps money should never be discussed in front of other people. Perhaps debt is always shameful, expensive gifts demonstrate love, or a person who works hard deserves the freedom to spend. Maybe you believe every household should maintain a substantial savings cushion, or that refusing small pleasures is a miserable way to live. Some of these beliefs may have served you extremely well. Others may cause unnecessary tension, particularly when circumstances change. The difficulty is that an inherited rule rarely announces itself as inherited. It simply appears in your head as the correct response, often accompanied by considerable impatience toward anyone who disagrees.
The household where money first acquired meaning
Children learn about money partly through what adults say and partly through what adults repeatedly do. A parent may insist that savings are essential while routinely making expensive purchases without planning. Another may describe money as unimportant while becoming visibly distressed whenever an unexpected bill arrives. Children don't necessarily absorb these contradictions in the same way. One might decide that financial caution is essential; another might become determined to avoid a life dominated by money worries. Two people raised in the same household can develop strikingly different spending habits because their experiences, temperaments, and interpretations are not identical.
Consider a family where income fluctuates from month to month. During good periods, the household feels relaxed. During difficult periods, adults become anxious and certain purchases are postponed. A child might conclude that the safest response is to save aggressively whenever money is available. Another child might reach the opposite conclusion: opportunities should be enjoyed while resources exist because tomorrow is uncertain. Both responses can develop from the same circumstances. This doesn't establish a clinical explanation for either person's adult behavior, and it certainly doesn't make their future decisions inevitable. It does show why the claim "Anyone raised properly would understand this" is a particularly unreliable contribution to a money argument.
The messages surrounding financial success can be equally influential. Some families praise modesty and quietly criticize people who display wealth. Others treat visible purchases as evidence of progress and ambition. A person raised with the first message may feel uncomfortable buying something expensive even when the purchase is affordable and useful. Someone familiar with the second may associate financial achievement with the ability to upgrade their lifestyle. Neither necessarily believes they are trying to impress anybody. The meaning attached to a purchase may simply feel natural. One person buys a reliable, understated car and feels successful because they avoided unnecessary expense. Another chooses a more luxurious vehicle and feels successful because years of effort have produced a tangible reward.
Family attitudes also shape expectations about sharing. In some households, money earned by adults is understood primarily as a resource for the whole family. In others, individual earnings and personal financial independence are emphasized. Neither arrangement automatically determines whether a household is loving, cooperative, or fair. Problems arise when partners assume they share the same understanding without ever discussing it. One might consider helping relatives a natural obligation, while the other sees financial support as something requiring careful limits. These differences become particularly sensitive because questioning a financial decision can sound like questioning someone's loyalty, upbringing, or love for their family.
It's tempting to resolve all this by deciding that one family taught better lessons than the other. Unfortunately, family habits aren't competing instruction manuals with a single answer sheet. They developed under different circumstances and often responded to challenges that no longer exist. A rule that protected a household during years of unpredictable income may become unnecessarily restrictive when two reliable salaries are available. Conversely, a relaxed approach that worked in a family with substantial financial support may create difficulties for a couple without that safety net. The useful question is whether a particular belief suits your present responsibilities, rather than whether your parents would approve of the way your partner buys groceries.