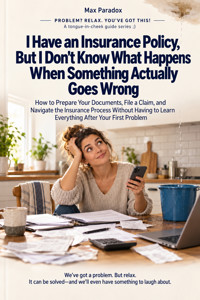
I Have an Insurance Policy, But I Don't Know What Happens When Something Actually Goes Wrong - How to Prepare Your Documents, File a Claim, and Navigate the Insurance Process Without Having to Learn Everything After Your First Problem ebook
Max Paradox
29,99 zł
19,90 zł
Najniższa cena z 30 dni przed obniżką: 29,99 zł
19,90 zł
Najniższa cena z 30 dni przed obniżką: 29,99 zł
Dowiedz się więcej.
- Wydawca: ALL-IN Rafał Płonkowski
- Kategoria: Biznes, rozwój, prawo•Biznes, rozwój
- Język: angielski
You have insurance. Wonderful. Now, what exactly happens when you need to use it?
Most people feel reasonably protected after buying an insurance policy. They pay the premium, receive a confirmation email, and file the documents somewhere they'll definitely remember. Then something goes wrong. Suddenly, they're expected to understand coverage conditions, exclusions, deductibles, claim forms, damage estimates, and settlement decisions.
Apparently, owning insurance also requires an unofficial degree in administrative archaeology.
In I Have an Insurance Policy, But I Don't Know What Happens When Something Actually Goes Wrong, Max Paradox takes readers through the insurance claims process with practical explanations, relatable situations, and the kind of humour that makes complicated paperwork slightly less intimidating.
This is a guide for anyone who wants to understand what their insurance actually does, prepare before trouble arrives, and avoid learning every important lesson while already dealing with a loss.
You'll discover how to recognize the difference between the protection you think you purchased and the coverage your agreement actually provides. You'll learn which documents are worth keeping, how to organize important information without creating a second job for yourself, and what to do during the first hours after an unexpected incident.
The book explains how to document damage, preserve useful evidence, and submit a claim without guessing facts simply because an online form demands an answer. It also shows how to communicate with insurers, understand requests for additional information, and distinguish genuine progress from another reassuring message announcing that your claim is "under review."
And when the decision finally arrives?
You'll learn how to examine the explanation, understand the difference between coverage and valuation, identify possible errors, and prepare a focused complaint when reconsideration is justified.
Max Paradox also explores the situations that rarely fit neatly into a claims form: missing receipts, incomplete evidence, damaged property belonging to someone else, several companies disputing responsibility, and claims that become complicated when illness or injury leaves little energy for administration.
The practical guidance continues beyond the payment itself. What happens when repair costs change? What should you understand before signing a final settlement? What if a repaired item develops another fault? And how can you review your insurance afterwards without turning ordinary life into a permanent disaster-planning exercise?
Throughout the book, fictional everyday examples reveal the small misunderstandings and rushed decisions that can make an already difficult situation more expensive.
There are no magical phrases guaranteed to make insurers pay, no promises that every loss is covered, and no expectation that readers should become legal or insurance professionals. Policies and legal rules differ, and some situations require specialist advice.
Instead, you'll find a clear, realistic approach to understanding your options, asking better questions, and making informed decisions.
Because insurance should help you manage unexpected problems, not require you to develop an entirely new personality dedicated to chasing documents.
Read this book before your next claim, not while searching desperately for a policy number with one hand and holding a leaking bucket with the other.
This publication was prepared using tools that support the creative process, including artificial intelligence solutions. The final concept, structure and editing are the responsibility of the author.
Ebooka przeczytasz w aplikacjach Legimi lub dowolnej aplikacji obsługującej format:
Liczba stron: 250
Rok wydania: 2026
Podobne
Cover
I Have an Insurance Policy, But I Don't Know What Happens When Something Actually Goes Wrong
How to Prepare Your Documents, File a Claim, and Navigate the Insurance Process Without Having to Learn Everything After Your First Problem
Max Paradox
PROBLEM? RELAX. YOU'VE GOT THIS!
ISBN: 978-83-8483-802-0
ALL-IN Rafał Płonkowski
Table of contents
Title page
INTRO
Chapter 1 - You Bought an Insurance Policy, Not an Invisible Force Field
Chapter 2 - From Disaster to Payment: What Actually Happens Between the Two?
Chapter 3 - The First Few Hours: How to Stop a Bad Day from Becoming an Expensive Disaster
Chapter 4 - Insurance Myths, Miracle Tricks, and Other Excellent Ways to Make Things Worse
Chapter 5 - The Documents You Definitely Have Somewhere: Preparing Before Anything Goes Wrong
Chapter 6 - Thirty-Seven Photographs and Still No Proof: Collecting Evidence That Actually Explains Something
Chapter 7 - Is Anybody Actually Handling My Claim? How to Communicate Without Becoming a Full-Time Insurance Detective
Chapter 8 - Repair It, Throw It Away, Sign Here: Decisions You Shouldn't Make in a Panic
Chapter 9 - Filing a Claim Without Turning the Form into a Work of Fiction
Chapter 10 - The Price of a Disaster: Why the Repair Estimate and the Insurance Payment May Disagree
Chapter 11 - The Decision Has Arrived. Unfortunately, It Seems to Be Written in Another Language
Chapter 12 - Writing a Complaint That Gives Someone a Reason to Change Their Mind
Chapter 13 - Someone Else Caused the Damage. So Why Are You Still Doing All the Work?
Chapter 14 - The Money Has Arrived. Why Is Your Claim Still Sitting at the Kitchen Table?
Chapter 15 - The Claim Is Real, but the Evidence Has Disappeared: What to Do When You Can't Prove Everything
Chapter 16 - When Life Falls Apart, Paperwork Doesn't Become Easier: Managing a Claim During a Personal Crisis
Chapter 17 - One Accident, Four Companies, and Nobody in Charge: Untangling a Complicated Insurance Claim
Chapter 18 - Renewal Is Not a Time Machine: Keeping Your Insurance Useful When Your Life Changes
Chapter 19 - The Claim Is Closed, but the Problem Hasn't Got the Message: Recognizing When Something Is Going Wrong Again
Chapter 20 - You Don't Need to Become an Insurance Expert: How to Handle the Next Surprise Without Starting from Zero
Landmarks
Cover
Title page
Table of contents
Start of content
INTRO
Your suitcase appears on the airport baggage carousel looking as though it has survived a disagreement with an industrial wood chipper. One wheel is missing, the handle is bent, and a suspiciously large section of the zipper has surrendered. A shirt is hanging through the opening, waving gently at the other passengers like a tiny flag of defeat. You stare at it, hoping there has been a mistake. Unfortunately, the luggage tag confirms that this battered object is yours. Your travelling companion offers the sort of reassurance people give when they have absolutely no idea what comes next: "Well, at least we've got travel insurance."
Wonderful. You do have travel insurance. You remember buying it. You remember comparing prices, selecting a package, and feeling impressively responsible when the confirmation email arrived. You may even have paid extra for enhanced baggage protection, although the precise details now occupy the same inaccessible region of your memory as the password to your first email account. The question is what to do with that insurance now. Should you report the damage to the airline before leaving the airport? Contact the insurer first? Take photographs? Keep the damaged suitcase? Buy a replacement? Is the missing wheel covered? And what exactly does the policy mean by "accidental damage to personal baggage"?
Meanwhile, the baggage carousel stops moving. The airport staff begin preparing for another flight. Your travelling companion is hungry, your phone battery is declining, and the only thing you know for certain is that your suitcase will not be rolling anywhere without considerable encouragement. Apparently, purchasing financial protection was the easy part. Using it requires an entirely different set of skills, none of which appeared on the cheerful confirmation screen when you paid your premium.
This is the strange bargain most of us make with insurance. We spend money today to reduce the financial consequences of something unpleasant happening tomorrow, then quietly hope never to discover how the arrangement works in practice. We recognize the importance of being insured, but rarely devote much attention to what happens between an incident and an actual payment. The policy arrives, we save it somewhere sensible, and life continues. "Somewhere sensible" often means an email folder containing 14,000 unread messages and several promotional offers for products we have never wanted. Everything feels perfectly organized until we need a particular document immediately.
The difficulty is not necessarily that insurance companies make every process unnecessarily complicated, or that policyholders are incapable of following instructions. Insurance involves genuinely different kinds of risks, responsibilities, evidence, and contractual conditions. A policy can provide valuable protection while still excluding certain circumstances. An insurer may reasonably request information that a customer never thought to preserve. A legitimate claim can take time to assess, and an apparently straightforward incident may involve questions that cannot be answered by looking at one photograph. The trouble begins when we encounter all these distinctions for the first time while already dealing with a damaged possession, an unexpected expense, or something far more serious.
Consider how we usually buy insurance. We compare premiums, look at coverage amounts, examine a handful of benefits, and sometimes read customer reviews. These are useful steps, but they don't necessarily reveal how we would actually use the product. A high coverage limit may sound reassuring, even though individual categories of property have lower limits or special conditions. An assistance service may be included, but only for specified situations. A claim might require contacting another organization before important evidence disappears. None of these details automatically makes the insurance bad. They simply demonstrate that having a policy and understanding how to use it are two different accomplishments.
This book is for people who would prefer not to develop an unexpected second career in insurance administration. You don't need to become an adjuster, memorize contractual definitions, or learn to enjoy correspondence containing phrases such as "subject to the applicable exclusions." You need something much more practical: a way to recognize which information matters, what action should come first, how to communicate clearly, and when an answer deserves closer examination. If you're already dealing with a claim, that knowledge can help you make sense of the situation. If nothing has happened yet, it can help you prepare without turning ordinary life into a permanent emergency-planning exercise.
Preparation does not mean keeping a photographic inventory of every object you own or rehearsing hypothetical disasters every Sunday afternoon. It means making a few thoughtful decisions while you have the time and energy to make them. Where are your current policy documents? Which insurer provides which protection? How can you find the relevant claims procedure? What evidence would be difficult to reconstruct after a loss? You can answer these questions without developing a filing system sophisticated enough to qualify as a small government department. The aim is to reduce avoidable confusion, not replace your existing responsibilities with a lifelong commitment to managing folders.
You will also learn why certain instinctive reactions can make an already difficult situation harder. Some people immediately repair or dispose of damaged property without considering whether its condition needs to be examined. Others become so worried about making a mistake that they delay sensible steps to prevent further damage. Some write extremely long descriptions containing every emotional detail but very few facts. Others submit almost nothing, believing that a policy number should give the insurer access to a complete reconstruction of the event. A more useful approach is to understand what each action is meant to accomplish. Protecting people, limiting additional harm, preserving relevant information, and meeting applicable notification requirements are connected responsibilities, but their urgency and practical demands can differ.
An equally important skill is learning how to respond when the process does not go as expected. You might receive a request for documents you cannot find, an estimate that seems unreasonably low, or a decision you struggle to understand. The answer isn't automatically to accept everything, nor is it to declare war on the insurer's customer service department. Often the most productive first step is identifying precisely what has been decided, what information supports that decision, and where your understanding differs. A polite, well-supported question can be more useful than an angry six-page email. Capital letters may communicate frustration, but they do not increase the evidential value of a repair estimate.
There are limits to what any general guide can promise. Different insurance products operate under different terms, and relevant laws vary between jurisdictions. The appropriate response to a serious injury, major financial loss, disputed liability, or complex legal question may require qualified professional advice. Even excellent documentation cannot guarantee a payment if an event falls outside the applicable protection. This book won't offer secret phrases that force an insurer to approve every claim. It will help you recognize the difference between a problem you can resolve with clearer information and one requiring specialist judgment. Knowing that difference is part of being prepared.
Return to the airport for a moment. Your suitcase is still damaged, and your holiday has acquired an irritating administrative subplot. But imagine knowing to check the airline's reporting procedure before leaving, preserve useful evidence, locate the relevant insurance terms, and avoid assuming that every replacement purchase will automatically be reimbursed. You still need to establish what happened, which responsibilities apply, and what protection is available. Yet instead of facing one enormous mystery, you have a series of manageable questions. That doesn't repair your luggage, but it changes the way you deal with the problem.
And that is the real purpose of this book. You cannot prevent every accident, guarantee that every claim will be approved, or persuade the universe to respect your carefully arranged schedule. You can become someone who knows how to approach an insurance problem without making it unnecessarily worse. You can ask better questions, recognize your options, and act with more confidence when circumstances are anything but convenient.
Insurance is supposed to help manage uncertainty. Understanding how to use it should not require you to become a completely different person.
Especially when all you originally wanted was to collect your suitcase and go on holiday.
Chapter 1 - You Bought an Insurance Policy, Not an Invisible Force Field
At 8:43 on a perfectly ordinary Tuesday, Daniel knocks a mug of coffee across his desk. The coffee performs an impressive aerial manoeuvre before landing directly on his laptop keyboard. For one hopeful second, the computer continues working. Then the screen flickers, the fan makes a noise suggesting urgent mechanical distress, and everything goes black. Daniel stares at the machine. He presses the power button, which achieves precisely nothing. Then he remembers something wonderful: when he bought the laptop, he paid extra for a protection package. The salesperson had described it as comprehensive. Daniel had even congratulated himself on making a sensible financial decision. Surely, somewhere in the insurance industry, a small team is already preparing to rescue him.
Unfortunately, the documentation is less enthusiastic. The protection package covers certain mechanical and electrical failures under specified conditions, but accidental liquid damage is not included. The exact product is a service plan rather than the accidental-damage insurance Daniel imagined he had purchased. His laptop is still dead, his coffee is cooling on the floor, and the additional protection he paid for offers no obvious solution to this particular incident. He feels cheated, although he cannot remember anyone explicitly promising coverage for spilled drinks. What he remembers is the word "comprehensive", delivered with the confidence of a person who knew that the checkout line was getting longer.
This is the first lesson of insurance ownership: the protection you believe you purchased and the protection your agreement actually provides may be different things. That doesn't necessarily mean anyone lied. Sometimes a product was poorly explained, sometimes the customer misunderstood an important distinction, and sometimes the sales process genuinely deserves closer scrutiny. Whatever the explanation, the consequences usually become visible at the worst possible moment. A policy is not a universal promise that unpleasant financial surprises will be eliminated. It is a specific agreement defining which risks are covered, under what conditions, for whom, and subject to which limits.
Think of insurance as a carefully designed financial arrangement rather than a general-purpose emergency fund. The insurer agrees to assume certain defined risks in exchange for a premium. You receive protection against events that satisfy the applicable conditions. Everything outside those conditions requires separate consideration. This sounds obvious when stated calmly, but advertising rarely encourages customers to imagine the full boundaries of their protection. Nobody wants a billboard announcing, "We offer excellent coverage, provided your circumstances fit the relevant definitions and you haven't encountered an exclusion." Yet those qualifications matter far more than the cheerful photograph of a relaxed family appearing beside the price.
What the paperwork is actually trying to tell you
The first practical challenge is discovering what constitutes your insurance agreement. People often refer to "the policy" as though it were a single document containing every relevant answer. In reality, the applicable terms may be spread across a policy schedule, declarations, general conditions, additional endorsements, certificates, and documents recording later changes. The terminology varies between providers and jurisdictions. A coverage summary may be useful, but it should not automatically be treated as a complete statement of contractual rights. Similarly, an advertising leaflet describing the most attractive benefits might omit qualifications that appear in the full terms.
Start by identifying the particular product you hold and the documents that apply to it. A provider may sell several versions of an apparently similar package. Its website might display current terms that differ from those issued when you purchased your protection. An endorsement may expand or restrict a particular section without changing the document's familiar product name. If you cannot identify which version governs your agreement, asking the provider for confirmation is more useful than guessing from search results. Reading the wrong policy conditions with tremendous concentration is still reading the wrong policy conditions, although it may give you a misleading sense of achievement.
Next comes the question of who is actually protected. The policyholder, the insured person, the owner of the property, and the person entitled to receive payment are not necessarily the same individual. Consider a household containing two adults, a visiting relative, and a student temporarily living elsewhere. Whether particular people or possessions fall within the protection may depend on the contract's definitions, their circumstances, and where the incident occurs. Do not assume that everyone sharing an address automatically enjoys identical cover. Family relationships can be wonderfully flexible at holiday dinners. Insurance definitions tend to prefer a little more precision.
The same care applies to the property or interest being insured. Home insurance may distinguish between the building, personal belongings, additional structures, and liability to other people. A vehicle policy may provide protection for third-party liability without paying for accidental damage to your own vehicle. Travel insurance might include medical assistance, cancellation benefits, and baggage coverage, each governed by separate conditions. These distinctions are not minor administrative details. They determine which part of an agreement might respond to a specific problem. Owning several insurance products does not create one enormous combined policy that automatically covers anything unfortunate.
Then there is the wording used to describe covered events. Some policies identify particular insured perils, while broader forms of protection may cover accidental loss or damage unless an exclusion applies. Even the phrase "all risks" should not be interpreted literally as every conceivable risk without qualification. Definitions, exclusions, limitations, and other conditions still matter. A theft, disappearance, accidental breakage, and mechanical failure can be different events for insurance purposes, even when they all produce the same practical result: something valuable is no longer available for you to use. The ordinary meaning of a word may not fully capture the definition adopted by the relevant agreement.
A useful reading habit is to move beyond the attractive list of benefits and find the corresponding conditions. If the summary mentions theft protection, determine what kinds of theft are covered and whether particular security requirements apply. If it promises emergency accommodation, establish which events trigger the benefit and what limitations exist. If accidental damage appears as an optional extra, check whether it was actually selected. You are not searching for reasons to distrust every sentence. You are establishing the difference between a product's general description and the specific promise on which you can reasonably rely.
Large numbers, small qualifications
Insurance schedules frequently contain impressive figures. A homeowner might see a substantial building coverage limit and assume that virtually every damaged item on the property is financially protected. Unfortunately, the headline amount may be subject to separate limits for particular categories, events, or additional benefits. There may also be an overall maximum for the relevant coverage section. A generous limit for the building does not necessarily extend unchanged to jewellery, business equipment, or property kept away from home. The largest number on the first page is not a universal spending allowance.
Deductibles and excesses deserve equally close attention. Depending on the agreement and jurisdiction, these arrangements may require you to bear an initial portion of a covered loss or otherwise affect how a payment is calculated. Other provisions may establish thresholds or special limits. The practical result is that a loss costing a certain amount to repair may produce a smaller insurance payment. Before deciding that a quotation represents good value, consider what financial responsibility remains with you. A cheaper premium may be entirely sensible if you can comfortably absorb the corresponding deductible. It is less attractive if the deductible becomes a surprise precisely when your emergency savings are already under pressure.
Another commonly overlooked distinction concerns how damaged property is valued. An agreement may use replacement-cost provisions, actual cash value, agreed value, repair-cost calculations, or other methods. These terms do not necessarily mean the same thing, and their application can depend on the property, the type of loss, and additional conditions. If you bought an expensive television several years ago, its original purchase price might not automatically equal the amount payable following a covered loss. Conversely, certain replacement-cost arrangements may work differently from simple depreciation-based calculations. The right question is not merely "How much did I pay?" but "How does this agreement determine the amount payable?"
Time and location also create important boundaries. Coverage may begin on a specified date rather than at the moment you first discussed the product. Certain benefits may involve waiting periods. Protection for possessions at home might operate differently when the same items are taken abroad, stored temporarily, or used for commercial purposes. A change in how property is occupied or used can also affect particular contracts. None of this means you must report every alteration in your daily routine. It means identifying which circumstances the policy treats as relevant and checking the applicable obligations when those circumstances arise.
Daniel's laptop provides another useful distinction. An extended manufacturer's warranty, a retailer's service agreement, and insurance against accidental damage may offer overlapping benefits, but they are not interchangeable. Their contractual structures, exclusions, service arrangements, and remedies can differ. Consumer rights concerning defective goods may also exist independently of optional protection products, depending on the applicable law. If a laptop develops an inherent defect, the appropriate route may differ from the response to coffee being poured over its keyboard. Mixing every possible remedy into a single vague idea of "warranty insurance" is convenient only until somebody asks which agreement actually applies.
Insurance against liability is another source of confusion. Suppose a visitor slips on your property and demands compensation. Having liability insurance doesn't automatically establish that you are legally responsible, nor does the visitor's demand automatically become an insured claim. The circumstances and applicable legal rules must be considered, along with the policy's coverage. Likewise, buying insurance for the structure of your home does not necessarily protect you against every claim brought by another person. It is essential to distinguish protection for your own losses from protection relating to your liability for losses suffered by others.
Read the policy from a possible problem backwards
Trying to memorize an entire policy can be exhausting and surprisingly unproductive. A more useful approach is to identify a realistic situation that matters to you and trace how the agreement would address it. Suppose you depend on a specialist camera for your work. Ask whether that camera is included, whether business use affects protection, which types of damage are covered, whether protection applies away from the declared premises, and what limits or deductibles might apply. You may discover excellent coverage. You may uncover a gap. Either answer is more useful than the comforting assumption that your possessions are protected because the annual premium was paid.
For each important policy, aim to understand six essential features: the people covered, the property or risks insured, the main triggering events, important exclusions, financial limits, and the period and geographical scope of protection. These are not substitutes for the full agreement. They are a way of identifying its practical boundaries. When an answer remains uncertain, record the actual question and request clarification from the insurer or intermediary. A written explanation linked to your particular policy is usually more useful than a friend's recollection of a vaguely similar claim from several years earlier.
What if you discover that your existing protection is unsuitable? You can investigate alternatives, amendments, or additional coverage before another incident occurs. Do not assume that purchasing an extension after damage will make the earlier event covered. Effective dates, eligibility conditions, and other contractual provisions matter. You might also decide that certain small losses are affordable without insurance, while others would be financially difficult to manage. A thoughtful insurance decision involves choosing which risks to transfer and which to retain, not automatically purchasing every optional benefit offered during checkout.
Daniel eventually discovers that his laptop protection does not provide the accidental liquid-damage benefit he expected. That is disappointing, but understanding the reason allows him to consider the correct avenues for assistance rather than repeatedly submitting the same request under the wrong assumptions. He can also make a more informed decision when replacing the device. The lesson isn't that every expensive protection package is worthless, or that every company deliberately hides exclusions. It is that the real value of an agreement lies in the situations it actually addresses, not the confidence inspired by its name.
A policy can be extremely useful without being a force field. It can protect your finances against specified events while leaving other risks entirely with you. Understanding that boundary before something goes wrong is an ordinary but powerful advantage. And if the next salesperson assures you that a protection package covers "pretty much everything", you now have an excellent follow-up question: "Excellent. Could you show me exactly what 'pretty much' means?"
Chapter 2 - From Disaster to Payment: What Actually Happens Between the Two?
At 6:15 on Thursday evening, a hailstorm turns a quiet suburban car park into something resembling a particularly aggressive percussion concert. Ice pellets bounce off windscreens, rattle across metal roofs, and send pedestrians sprinting towards the nearest shelter. Fifteen minutes later, the weather clears. Olivia returns to her car and discovers that the bonnet, roof, and several body panels are covered in small dents. The vehicle is still drivable, but it looks as though somebody has attempted to improve its appearance using a bag of golf balls and a deeply misguided artistic vision. Olivia has comprehensive motor insurance, so she photographs the damage and opens her insurer's app. She expects to report the incident, receive an estimate, and arrange repairs. Simple enough.
Three weeks later, she has received a claim reference, two requests for additional photographs, an appointment with an assessor, and a message explaining that the repair estimate is being reviewed. The repair shop has offered a provisional date but cannot confirm the work until the arrangements are settled. Olivia is not necessarily being treated unfairly, yet she has no clear idea what the insurer is currently doing. She understands that the damage occurred, that she has a policy, and that someone ought to be dealing with the consequences. What she cannot see is the process connecting those facts. The claim has entered an administrative machine whose internal workings appear to require a security clearance and a working knowledge of ancient symbols.
The first thing to understand is that an insurance claim is not simply a request for money. It is a process for establishing whether a particular event creates an obligation under an insurance agreement and, if so, what that obligation involves. Depending on the product, the outcome might be a cash payment, an arranged repair, a replacement item, an assistance service, or another contractual benefit. The stages vary, and not every claim requires extensive investigation. Still, most claims involve some combination of notification, information gathering, coverage assessment, evaluation of the loss, a decision, and settlement. Once you understand the purpose of those activities, the process becomes less mysterious, even when it remains frustratingly slow.
Why reporting a loss is not the same as proving a claim
Olivia's first responsibility is to respond appropriately to the situation. Her car is safely parked, nobody is injured, and the immediate storm has passed. She can therefore gather relevant information without creating additional danger. If the incident involved injuries, an unsafe vehicle, or a serious continuing hazard, the priorities would be different. Safety and preventing further harm come before insurance paperwork. The insurer may also expect reasonable steps to limit additional damage, subject to the applicable terms and circumstances. What those steps involve depends on the particular event. A damaged vehicle that is unsafe to drive should not be taken onto the road simply because its owner wants to reach an approved repairer before closing time.
Next, Olivia needs to establish which protection might respond. Comprehensive motor insurance commonly addresses certain kinds of accidental damage to the insured vehicle, but its precise scope differs between policies. Whether hail damage is covered must be checked against the applicable terms, including any relevant exclusions, deductibles, and conditions. The fact that a claim seems obvious to the customer does not eliminate this step. Nor does it mean the insurer can ignore the actual agreement. Insurance operates through defined obligations, not a contest in which the person sounding most confident gets to decide what is covered.
When Olivia submits her notification, she gives the insurer enough information to identify the agreement and understand the reported event. She provides the relevant date and location, describes the storm and the visible damage, and supplies the requested photographs. She does not need to estimate the precise force of each hailstone or explain atmospheric conditions like a television meteorologist. The useful information concerns what happened, what was affected, and which circumstances can be established. Where something is unknown, it should remain unknown until there is a reasonable basis for clarification. A convincing story is not a substitute for accurate facts, even when the convincing story would be much more entertaining.
A claim reference is normally an administrative identifier, not a promise of payment. Confirmation that the insurer has registered the incident means the information has entered the relevant process. The company may still need to establish coverage, evaluate damage, or request additional material. Likewise, an appointment with an assessor does not necessarily mean liability has been accepted. These distinctions matter because customers understandably read signs of progress as signs of success. Unfortunately, a message saying "your claim is being processed" contains fewer financial commitments than a takeaway receipt saying "your order is being prepared".
What happens while the claim is being assessed?
The assessment process generally addresses two broad questions. First, does the insurance agreement respond to the circumstances reported? Second, if it does, what benefit or payment is due? Those questions can involve different kinds of information. Coverage assessment may require the policy terms, relevant facts, and details about the cause of damage. Valuation may require repair estimates, technical assessments, invoices, or other evidence. The insurer might investigate both questions at the same time, but they remain conceptually distinct. Establishing that a hailstorm damaged a car does not automatically establish the cost of repairing every dent, and establishing the cost does not independently prove that the policy covers the event.
In Olivia's case, an assessor may examine the body panels and compare the visible damage with the reported circumstances. A repairer may then propose a method of restoring the vehicle. Some dents might be suitable for a particular repair technique, while others require different work. The assessor's observations and the repairer's estimate help inform the evaluation, although their roles and authority depend on the insurer's arrangements. The person inspecting a car does not necessarily have the authority to promise the final payment. A friendly comment such as "that should be straightforward" may be encouraging, but it should not be mistaken for a binding decision about coverage or cost.
Sometimes the insurer asks for documents that the customer considers unnecessary. A request may be reasonable because an important question remains unanswered. It might also be unclear, repetitive, or insufficiently connected to the claim. The useful response is to identify what the document is supposed to establish. If Olivia is asked for an earlier repair invoice, she can ask whether the insurer is investigating pre-existing damage or another specific issue. Understanding the purpose helps her provide relevant information without submitting every automotive document accumulated since buying the vehicle. Her service history is important, but the insurer probably does not need proof that she once purchased novelty air fresheners shaped like pineapples.